A clear look at the common types of auto cover and what each one actually does for you.
Every policy is a mix of parts, and each part answers a different what if. Once you understand them, it is far easier to keep the protection that matters and skip the extras that do not fit. Here is how I break down the main pieces.
The base most states require a driver to carry. It steps in for injury or damage caused to another person or their vehicle, keeping those costs from landing on you after a crash you cause.
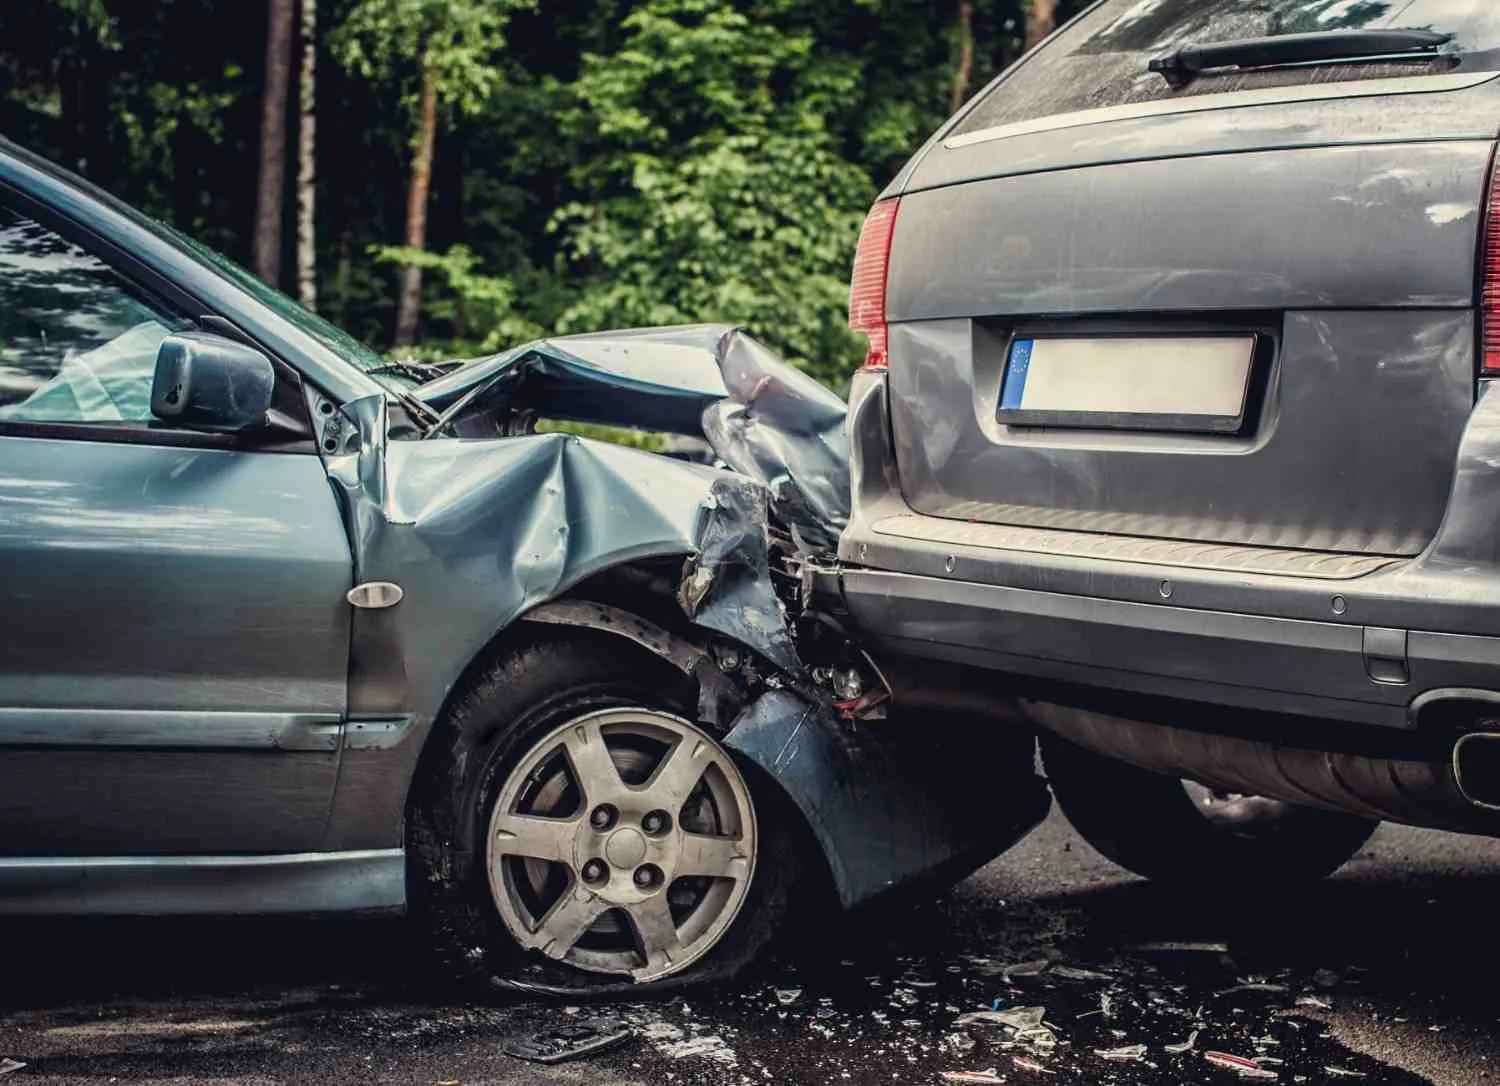
Handles repairs when your car meets another vehicle or a fixed object, regardless of who was at fault. A sensible pick for newer or financed rides where repair bills can climb quickly.
A wider net that adds theft, fire, weather, and vandalism on top of everyday collision cover. It reaches the situations that have nothing to do with another driver being involved.
Smaller pieces that can round out a plan when they fit the way you drive.
Steps in when someone without a policy causes a crash, so repair and medical costs do not fall on you.
Covers the everyday roadside snags, from a flat tire to a tow, when a trip does not go to plan.
Helps with medical costs for you and your passengers after an incident, no matter who was at fault.
Keeps you moving with a rental while your own car sits in the shop for covered repairs.
Bridges the difference between what a car is worth and what is still owed on it after a total loss.
Protects the value of a recent purchase so an early loss does not turn into an early setback.
A few things worth sorting out before settling on a plan.
It comes down to your car, how often it rolls, and what you could comfortably pay out of pocket after a rough day. Give me the short version of your situation and I will point you toward limits that fit, with no money wasted on extras you would never touch.
It is the amount you pay before I have your policy step in on a claim. Set it higher and the monthly cost usually eases, though you carry more at claim time. Set it lower and it flips the other way. I help you find the point that sits right with your budget.
Often there is, and I will point out the levers that fit you. Bundling vehicles, keeping a clean record, nudging a deductible, or catching discounts you already qualify for can all shave the cost while the core cover stays put.
Liability is usually required, while collision, full protection, and the extras are yours to choose. Whether they make sense depends on the age of your car, the loan behind it, and how much risk you feel right carrying yourself.
Tell me what you drive and how the miles add up, and I will give you a straight read on the coverage that suits you.
Start Your Quote